
What is the CIBIL Score
How CIBIL Score is calculated?
CIBIL is a corporation based in India that offers information pertaining to consumer financing in the country. The amount of money that a bank is willing to lend to a consumer is directly related to their CIBIL score. CIBIL scores are determined by a number of parameters, including but not limited to income, employment history, record of loan repayment, credit card repayment, etc. Scores on CIBIL are updated on a monthly basis. Your payment history, current debt level, age, income, work status, and other factors are taken into account when determining your CIBIL score. Your ability to make payments is one factor that is taken into consideration when looking at your CIBIL score. If your CIBIL score is good, it means that you have a history of making on-time payments for your debts. If your CIBIL score is poor, it indicates that you have missed some of your payments. If your CIBIL score is low, you will be required to make additional payments on top of what you already owe. If your CIBIL score is high, you can anticipate paying a lower amount than what you are currently obligated to pay back. Your Equated Monthly Installment (EMI) is another factor that is taken into consideration when your CIBIL score is being determined.How often Cibil score is updated
After completing an application, your CIBIL score will typically be determined within the following twenty-four hours. CIBIL scores are normally calculated anywhere from two to three months after a loan application has been submitted. In most cases, CIBIL scores are only calculated once every calendar year. When you apply for a new loan, CIBIL scores are frequently calculated as part of the process. The CIBIL score for your loan will be reassessed anytime there is a change made to it. Banks, NBFCs, housing finance companies, and other businesses use CIBIL scores. The CIBIL score is based on information from different places, like bank statements, credit card bills, pay stubs, etc. Summary- There are three digits in a CIBIL score.
- The range of CIBIL scores is from 0 to 900. Most of the time, a CIBIL score is given after 3 years of making payments.
- Every month, the CIBIL score is changed.
- Only people who want to borrow money can get a CIBIL score.
- CIBIL score is not mandatory.
- For some loans, you need a CIBIL score. The CIBIL score is not required for some loans.
Difference between CIBIL Score and Credit Score
CIBIL Score
A consumer’s credit profile can be understood by their CIBIL score, which is a three-digit numeric summary of the consumer’s credit history. On the other hand, CIBIL is a credit bureau that keeps records of all the credit-related actions of businesses and individuals. These records can be accessed by anybody. One of the four most important credit bureaus in India is called CIBIL. Equifax, CRIF Highmark, and Experian are the names of the other three credit bureaus. The Reserve Bank of India has issued licenses to each of India’s four credit bureaus (RBI). The credit rating that is determined by CIBIL and given a number is referred to as the CIBIL score.What exactly constitutes a credit score?
Your credit score is a numerical representation of how creditworthy you are as a prospective borrower. Your credit score is determined by taking into consideration your credit history, which includes the total amount of debt, the number of credit accounts, credit card bills, credit utilization information, and payback history, among other factors. When determining your credit rating, another factor that is considered is the number of times you have requested information about your credit history, such as when you applied for a credit card or a loan. The credit rating company TransUnion developed the CIBIL Score, which is a numerical representation of a consumer’s creditworthiness.Difference between CIBIL Score and CIBIL Report
Your CIBIL report is a report created by CIBIL that contains information about your CIBIL score as well as your debt accounts and the payments made on those accounts. It includes specifics such as the loans that you may have taken out in the past, the dues on your credit cards, and other financial obligations, as well as how you repaid them. Your CIBIL score is determined with the assistance of all of this information that is provided to CIBIL. In addition to the specifics regarding your financial obligations, it also contains your personal information, such as your name, address, Permanent Account Number (PAN), contact details, and so on.How to check the cibil score online
You can check your CIBIL Score online by visiting the official CIBIL website https://www.cibil.com Keep in mind, however, that in order to obtain limitless access to the CIBIL dashboard or to obtain customized loan offers, etc., you will need to subscribe to a plan, which will cost you a minimum of 550 Indian Rupees for a month.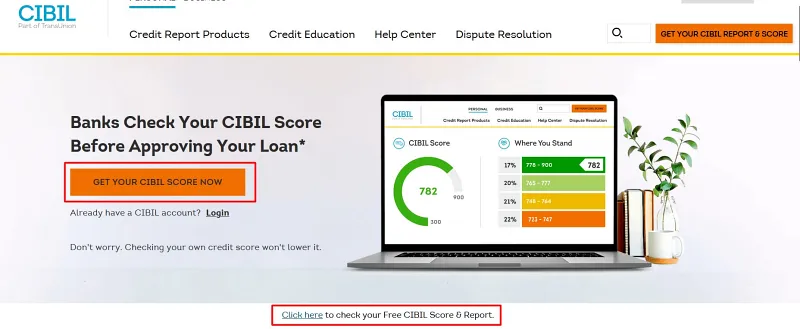
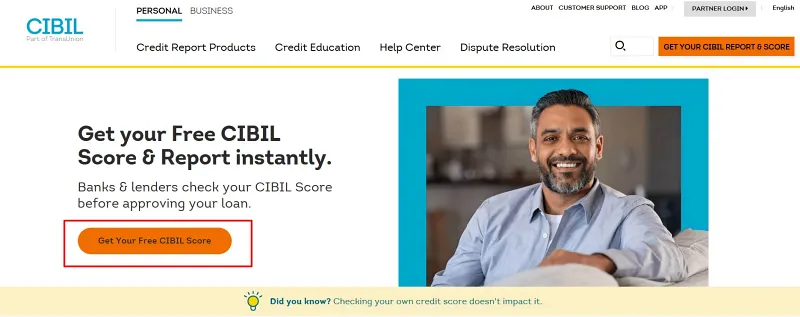 Now you will be redirected to a page where you have to fill your personal information to create an account.
Enter your Name, Email ID and Password and attach an ID Proof (Driver’s License Number, Passport Number, PAN Card, Aadhaar or Voter ID). Also enter your zip code, date of birth and Phone number.
- Now Click on ‘Accept and continue’ option
- You will receive an OTP on your given Mobile Number . Enter the OTP and select to ‘Continue’
- Select ‘Go to dashboard’ option and check your credit score
- Now you will be redirected to myscore.cibil.com
- Click on ‘Member Login’
- Once you log in, now you can see your CIBIL score.
Minimum CIBIL score to get Personal loan and Home loan
To qualify for a personal loan, a CIBIL score of at least 750 is required. To access more functions, you should have a CIBIL score that is close to 900. If your score is lower than 750, you will need to work on improving it. A CIBIL score between 650 and 749 is required as a bare minimum to qualify for a mortgage loan. Any score higher than 750 is regarded to be satisfactory.How to maintain good CIBIL score
The following are some easy steps that can be taken to keep your CIBIL score in good standing.- By making on-time payments of your installments, you can keep a solid record for yourself.
- Take responsibility for your credit card use and make purchases up to the limit at all times.
- If you are unsure about your ability to repay a debt, you should steer clear of co-signing for one.
- Avoid obtaining too much debit.
CIBIL Score Range :
Find below the Cibil Score and it’s value| CIBIL Score | Range |
| 300-579 | poor credit |
| 580-669 | fair credit |
| 670-739 | good credit |
| 740-799 | very good credit |
| 800-900 | exceptional credit |
🧮 Personal Loan EMI Calculator
Calculate your exact monthly EMI before applying — free and instant
Calculate Personal Loan EMI →Go to cibil.com and click Get Your Free CIBIL Score. Register with your name, PAN card number, date of birth, and mobile number. Verify via OTP and answer identity questions. Your CIBIL score and credit report appear on screen within 3-5 minutes. This is free once per year as per RBI guidelines.
No. Checking your own CIBIL score is a soft inquiry and does not affect your score in any way. You can check it as many times as you want without any impact. Only hard inquiries made by banks when you apply for a loan affect your score temporarily.
A CIBIL score of 750 and above is considered good in India. Most banks and lenders prefer 750+ for loan and credit card approvals at the best interest rates. A score of 800+ is excellent and gives you access to premium financial products. Score below 650 makes loan approval difficult.
PAN card is required to check CIBIL score on the official cibil.com website. However some third-party platforms like Paisabazaar and BankBazaar allow you to check using Aadhaar number or passport as alternative identity verification. Apply for a PAN card if you do not have one — it is free and takes 2-3 weeks via the NSDL or UTIITSL portal.
With consistent on-time payments and low credit utilization, most people see improvement within 3-6 months. From July 2026 RBI has mandated weekly credit bureau updates so improvements reflect faster. Significant score improvement from poor to good typically takes 12-24 months of disciplined credit behaviour.
Most banks including SBI, HDFC, and ICICI prefer a minimum CIBIL score of 700 to 750 for home loan approval. A score of 750 and above gives you the best interest rates and maximum loan amount. Some NBFCs may consider scores of 650 to 699 but at higher interest rates. Below 650 most lenders reject home loan applications.
CIBIL score is a type of credit score specifically provided by TransUnion CIBIL — one of four RBI-licensed credit bureaus in India. Other bureaus like Experian, Equifax, and CRIF High Mark also provide credit scores. Your score may vary slightly across bureaus. Most Indian banks check CIBIL score first so it is the most important one to monitor.
Download the OneScore app, Paisabazaar app, or your bank app like SBI YONO or HDFC Mobile Banking. Register with your PAN card and mobile number. Your CIBIL score appears on the dashboard instantly. These apps offer unlimited free CIBIL score checks throughout the year with no annual limit unlike the official cibil.com which gives one free check per year.
Also Read Other Banking Related Posts
- CIF Full Form in Bank
- Transfer Money from Credit Card
- Full Form of Bank Names
- KYC Full Form in Bank
- Bank Holidays in India
- List of Govt. Banks in India
- First Bank in India
- What is NEFT Form in Banking
- NACH Full Form in Banking
- What is a cancelled Cheque
- Difference between Credit Card and Debit Card
- Check CIBIL Score Online Free
CIBIL Score vs Credit Score — What Is the Difference?
| Feature | CIBIL Score | Credit Score (General) |
|---|---|---|
| Full Form | Credit Information Bureau India Limited | Generic term for any bureau score |
| Provided By | TransUnion CIBIL only | CIBIL, Experian, Equifax, CRIF |
| Score Range | 300 to 900 | 300 to 900 (varies by bureau) |
| Who Uses It | SBI, HDFC, ICICI, Axis — most banks | Depends on which bureau bank checks |
| Free Check | Once/year at cibil.com | Each bureau gives one free/year |
| Best Score | 750+ considered excellent | 750+ across all bureaus |
| Impact of Check | Zero — soft inquiry only | Zero — soft inquiry only |
How to Check CIBIL Score Free — Quick Comparison of All Methods
| Method | Best For | Free Checks | Time | Link |
|---|---|---|---|---|
| cibil.com (Official) | Most accurate — full report | 1 per year | 3-5 min | cibil.com |
| Paisabazaar | Unlimited free monthly checks | Unlimited | 2 min | paisabazaar.com |
| BankBazaar | Quick score check | Unlimited | 2 min | bankbazaar.com |
| SBI YONO App | SBI customers — no registration | Unlimited | 1 min | SBI YONO app |
| HDFC Mobile Banking | HDFC customers | Unlimited | 1 min | HDFC app |
| OneScore App | Detailed monthly tracking | Unlimited | 2 min | OneScore app |
| Paytm App | Paytm users | Unlimited | 1 min | Paytm app |
CIBIL Score Range 2026 — What Your Score Means
| CIBIL Score | Rating | Loan Approval Chances | Interest Rate |
|---|---|---|---|
| 750 – 900 | 🟢 Excellent | Very High — most banks approve instantly | Lowest rates available |
| 700 – 749 | 🟡 Good | High — most banks approve | Competitive rates |
| 650 – 699 | 🟠 Fair | Moderate — some banks approve at higher rates | Higher than average |
| 600 – 649 | 🔴 Poor | Low — most banks reject or require guarantor | Very high if approved |
| 300 – 599 | ⛔ Very Poor | Very Low — mostly rejected | Not applicable |
| -1 or 0 | ⚪ No History | No credit history — new to credit | Varies by lender |
Method 1 — Check Free CIBIL Score on Official cibil.com (Most Accurate)
This is your legal right under RBI guidelines. Every Indian gets one free CIBIL report per year directly from TransUnion CIBIL.
- Go to www.cibil.com and click Get Your Free CIBIL Score.
- Click Register and enter your full name, email, and mobile number.
- Enter your PAN card number and date of birth.
- Verify with the OTP sent to your registered mobile number.
- Answer 3-5 identity verification questions about your credit history.
- Your CIBIL score and full credit report appear on screen — also sent to your email.
- Download and save your report as PDF for future reference.
Important: The free annual report resets on January 1 each year. If you already used your free check in 2026, your next free one will be from January 1, 2027.
Method 2 — Check Free CIBIL Score on Third-Party Platforms (Unlimited Free Checks)
These platforms give you unlimited free CIBIL score checks throughout the year — no annual limit:
| Platform | Free Checks | What You Get | Best For |
|---|---|---|---|
| Paisabazaar.com | Unlimited | Score + report summary | Most popular, instant |
| BankBazaar.com | Unlimited | Score + credit factors | Easy to use |
| OneScore app | Unlimited | Score + detailed report | Mobile app users |
| HDFC Bank app | Unlimited | Score (HDFC customers) | HDFC account holders |
| SBI YONO app | Unlimited | Score (SBI customers) | SBI account holders |
| Paytm app | Unlimited | Score + basic report | Paytm users |
These platforms are free because they earn commission if you apply for a loan or credit card through them. Your score check itself is always free and does not affect your CIBIL score.
Method 3 — Check CIBIL Score via Bank Apps (Existing Customers)
If you already have a bank account, check your CIBIL score directly in your bank app — no separate registration needed:
- SBI YONO: Login → Services → Check Credit Score
- HDFC Mobile Banking: Login → Cards → Check CIBIL Score
- ICICI iMobile: Login → Credit Score → View Score
- Axis Mobile: Login → Credit Score → Check Now
- Kotak Mobile: Login → Credit Score section
New RBI Rule 2026 — Weekly CIBIL Score Updates
What this means for you:
- Good EMI payments reflect within 7 days — score improves faster
- Missed payments also show up faster — be more careful
- Loan repayment NOC reflects within 7-14 days after closure
- Check your score more frequently to track changes
What Factors Affect Your CIBIL Score?
| Factor | Weight | What Helps | What Hurts |
|---|---|---|---|
| Payment History | 35% | Pay all EMIs on time | Missing even one EMI |
| Credit Utilization | 30% | Use less than 30% of credit limit | Maxing out credit cards |
| Credit Age | 15% | Older accounts = better | Closing old credit cards |
| Credit Mix | 10% | Mix of secured and unsecured loans | Only one type of credit |
| New Enquiries | 10% | Apply for credit rarely | Multiple loan applications |
How to Improve CIBIL Score — 8 Proven Steps
- Pay all EMIs on time — every month without fail. Even one missed payment drops your score by 50-100 points. Set auto-pay or reminders.
- Keep credit card utilization below 30%. If your limit is Rs 1 lakh, never spend more than Rs 30,000 in a month.
- Do not close old credit cards. Old accounts increase your credit age — a key scoring factor.
- Avoid applying for multiple loans simultaneously. Each application triggers a hard inquiry that reduces your score temporarily.
- Check your credit report for errors. Wrong information is common — dispute and get it corrected immediately.
- Get a secured credit card if you have no credit history. Fixed deposit-backed cards help build credit from scratch.
- Maintain a mix of credit types. Having both a home loan and a credit card is better than only one type.
- Clear any overdue amounts immediately. Even small outstanding amounts severely damage your score.
How to Dispute Errors in Your CIBIL Report
Errors in credit reports are more common than most people think. Wrong loan entries, incorrectly marked defaults, or loans you never took can all appear. CIBIL must investigate and resolve disputes within 30 days by law.
- Go to cibil.com and login to your account.
- Go to Dispute Resolution section.
- Select the incorrect entry from your credit report.
- Choose the dispute reason and provide correct information.
- Upload supporting documents — bank statement, loan closure letter, NOC.
- Note your dispute reference number and track status online.
- Resolution comes within 30 days — CIBIL contacts the lender to verify.
If CIBIL does not resolve within 30 days, escalate to RBI Banking Ombudsman at cms.rbi.org.in or call 14448.
CIBIL Score for Home Loan, Personal Loan and Credit Card — 2026 Requirements
| Product | Minimum Score | Best Rate Score | Notes |
|---|---|---|---|
| Home Loan | 700 | 750+ | SBI, HDFC, LIC Housing prefer 750+ |
| Personal Loan | 650 | 750+ | Below 700 = higher interest rate |
| Credit Card | 700 | 750+ | Premium cards need 750+ |
| Car Loan | 700 | 750+ | Some NBFCs accept 650+ |
| Business Loan | 700 | 750+ | Also checks business financials |
| Education Loan | 650 | 700+ | Collateral-based loans more flexible |
CIBIL Score vs Other Credit Bureaus — Which to Check?
India has four RBI-licensed credit bureaus. Banks may check any of them:
| Bureau | Score Name | Check Free At | Banks Using It |
|---|---|---|---|
| TransUnion CIBIL | CIBIL Score | cibil.com | SBI, HDFC, ICICI, Axis — most banks |
| Experian | Experian Score | experian.in | Kotak, IndusInd, Federal Bank |
| Equifax | Equifax Score | equifax.co.in | HDFC, Citibank, Standard Chartered |
| CRIF High Mark | CRIF Score | crifhighmark.com | Microfinance lenders, NBFCs |
Check all four bureaus once a year — your scores may differ slightly. CIBIL is checked by most major banks so prioritize it first.
How to Check CIBIL Score by PAN Card Number — Step by Step
PAN card is the primary identity document required to check your CIBIL score. Here is the exact process using your PAN card number:
- Go to cibil.com or paisabazaar.com
- Click Get Free CIBIL Score or Check Credit Score
- Enter your 10-digit PAN card number (format: ABCDE1234F)
- Enter your full name exactly as on PAN card
- Enter date of birth, mobile number and email address
- Verify with OTP sent to your mobile
- Answer identity verification questions about your loans/cards
- Your CIBIL score displays instantly on screen
Can I check CIBIL score without OTP? No — OTP verification is mandatory for security. Make sure you use your registered mobile number.
| What You Need | Details |
|---|---|
| PAN Card Number | 10-digit alphanumeric (mandatory) |
| Mobile Number | Registered with Aadhaar or bank |
| Email Address | Active email for report delivery |
| Date of Birth | As per PAN card |
| Address | Current residential address |
Why Did My CIBIL Score Drop? — 7 Common Reasons
Many people are surprised when their CIBIL score drops without an obvious reason. Here are the most common causes:
- Missed or late EMI payment — Even one day late can trigger a negative mark. The impact is severe — 50 to 100 points drop.
- High credit utilization — Using more than 30% of your credit card limit signals financial stress to credit bureaus.
- Multiple loan applications in short period — Each application creates a hard inquiry that reduces score by 5-10 points each.
- Loan settlement instead of full closure — Settling a loan for less than full amount marks your account as “Settled” which is negative.
- Error in credit report — Wrong information added by a lender can lower your score unfairly. Check and dispute immediately.
- Closing old credit card — Reduces your total available credit and shortens credit history age — both negative factors.
- Co-signing or guaranteeing someone else loan — If they miss payments, it shows on your report too.
New RBI Rule — Compensation for Delayed CIBIL Score Correction
How to claim compensation for delayed CIBIL correction:
- File a dispute at cibil.com and note the dispute reference number and date.
- If not resolved within 30 days — file complaint against the lender at cms.rbi.org.in
- Mention the delay in days and request compensation at Rs 100 per day.
- The Banking Ombudsman will investigate and direct the lender to pay.
CIBIL Score for Self-Employed and Business Owners
If you are self-employed, a freelancer, or a business owner — your CIBIL score works the same way but lenders look at additional factors:
- Personal CIBIL score: Same 300-900 range — checked for personal loans and credit cards
- Business credit (CIBIL Rank): Separate ranking for companies — scale of 1 to 10 (1 is best)
- ITR requirement: Most banks require 2-3 years of IT returns for self-employed loan applicants regardless of CIBIL score
- Bank statement: 12 months of bank statements typically required alongside CIBIL score
- Minimum score for business loan: 700+ recommended — some NBFCs accept 650+
Self-employed tip: Maintain a separate business current account and keep personal and business finances separate. This helps build both personal and business credit profiles independently.
CIBIL Customer Care — Contact for Issues
| Contact Method | Details | Available |
|---|---|---|
| Customer Care Number | +91-22-6638-4600 | Mon-Fri 10AM-6PM |
| [email protected] | 24×7 (response in 2-3 days) | |
| Online Dispute | cibil.com/dispute-resolution | 24×7 |
| RBI Helpline | 14448 | 24×7 |
| RBI CMS Portal | cms.rbi.org.in | 24×7 |
How to Read Your CIBIL Report — What Each Section Means
Your CIBIL report has 5 main sections. Here is what to look for in each:
- Credit Score (top of report): Your 3-digit score. Aim for 750+. Also shows score history over last 24 months.
- Personal Information: Name, DOB, PAN, addresses, employer. Check for errors — wrong address or employer can cause identity issues.
- Account Information: All credit cards and loans — account number, lender name, amount, monthly payment status. Check for accounts you did not open (identity fraud signal).
- Enquiry Information: Every time a lender checked your credit in last 24 months. Too many enquiries = multiple loan applications = negative signal.
- Payment History: Month-by-month status for each account — Current (C), 30 days late (1), 60 days late (2), 90+ days (3). All should show C.